The Relationship between Environmental Management Practices and Environmental Performance: The Role of Organisational Culture
- School of Accountancy, Universiti Utara Malaysia
- School of Business Management College of Business, Universiti Utara Malaysia
Journal of Business Management and Accounting 3(1) (2013) · https://doi.org/10.32890/jbma2013.3.0.8883
Abstract
Nowadays, organisations and their management are working very hard to forecast and respond to ever-changing new markets and fierce competition. Due to increase in globalisation and technological advancements, the constant variable for today’s workplace is perhaps the ability to continuously evolve. Organisations must ensure that their activities do not harm or negatively impact the environment. This study investigated the effect of organisational culture on the relationship between environmental management practice and environmental performance. Organisational culture was measured using an adapted version of the Henri’s 2006 instrument which was based on a competing values perspective. Questionnaires were administered to 300 respondents (general managers/general managers) from various hotels in the Malaysian hotel industry. The hierarchical multiple regression method showed that organisational culture is not significantly related to environmental performance. However, to some extent, organisational culture has moderated the relationship between environmental management practice and environmental performance. This result implied that most of the sampled hotels in Malaysia employed a control dominant type of culture in achieving objectives. The results also showed even though hotels create an environmental culture in their activities, if people are not ready and not willing to share their knowledge toward creation of new values and beliefs, better environmental performance will not be achieved. This insignificant finding may be due to new beliefs relating to environmental issues in the Malaysian hotel industry.
Keywords: environmental management practice, environmental performance, organisational culture, Malaysia
1.0Introduction
Organisations nowadays are becoming more aware of considering and embedding environmental management practices (EMP) into their operations to overcome global competition. In addition to this, uncertainties in global markets require organisations to change their structure and process to adapt to this new environment, while at the same time attempt to achieve higher levels of performance. Environmental performance (EP) cannot sustain at current levels of economic activity (Wackernagel & Rees, 1996), if organisations do not change their organisational culture. Maria (2011) proved that organisational culture and performance are closely linked, and positive culture can provide a sign of competitive advantage (Sadri & Lees, 2001). Sorensen (2002) indicated that if an organisation maintains a strong culture by demonstrating a well-integrated and effective set of specific values, belief, and behaviour, then it will perform at a higher level of productivity.
From the environmental perspective, organisational culture is one of the variables that relates to the role and responsibilities of day-to-day tasks which is likely to help the organisation to solve problems related to environmental aspect. However, despite the claims that organisational culture plays a vital role in ensuring the improvement of environmental performance (Schein, 1990), little critical research attention (Bhimani, 2003; Henri, 2006) has been done to understanding the interaction effect of environmental management practice and organisational culture on environmental performance. Organisational culture and performance relationship had been examined by many scholars (Rousseau, 1990; Ogbonna & Harris, 2000; Henri, 2006) however, not much research has been done from the environmental perspective.
On the other hand, previous studies such as by Henri and Journeault (2006) examined environmental management practices within manufacturing firms, thus ignoring the significant impact of the service- based sector on environmental problems. As most of the empirical studies in Malaysia are on environmental management practices, such as by Baba (2004), Romlah et al. (2002), Jaafar (2001), and Foo and Tan (1988) who focused on firms listed on the Bursa Malaysia (that is manufacturing or construction industries), this study extends the practice to the service-based industry, e.g., the hotel sector. By focusing on service firms operating in developing countries, such as Malaysia, this study helps to advance an understanding of environmental management practice and organisational culture beyond its normal focus on the manufacturing and industrial sectors.
The purpose of this paper was to examine the role of organisational culture in the relationship between environmental management practice (EMP) and environmental performance (EP). The contribution of the current study is twofold; firstly, the study contributes to the environmental literature and organisational behaviour by examining the interaction effect of organisational culture and EMP on EP, and secondly, the study adopted the competing values framework as a dimension of organisational culture.
The remainder of the paper is structured as follows. The next section provides discussion on organisational culture, EMP, and EP, while the third section focuses on the research methodology. The findings are then discussed in the results section.
2.0Literature Review and Hypothesis
2.1Organisational Culture with Competing Values Framework
Previously, Deshpande and Webster (1989) defined organisational culture as a pattern of shared values and beliefs among people within an organisation. Eker and Eker (2009) also mentioned that organisational culture comprised values, beliefs, and norms which are shared by members of an organisation, and which consequently tend to influence the ideas, behaviours, and actions in their everyday work. The study adopted competing values framework (CVF) developed by The National Centre for Higher Education Management System, which was also used by Henri (2006), Eker and Eker (2009), and Agbejule (2011), where shared values pertain to dominant organisational attributes, importance of control, and the nature of information flow.
The competing value framework creates a shared meaning among people in the organisation and thus, produces similar behavioural norms. Generally, as discussed in Henri (2006) and Eker and Eker (2009), organisational culture is categorised into two types, which are control value culture and flexibility value culture. Control value culture refers to predictability, stability, formality, rigidity, and conformity. This type of value seems strict, tight, and focuses on a forcing through strategy, such as compliance to the law and regulations, and moving toward achieving goals. Meanwhile, flexibility value culture refers to spontaneity, change, openness, adaptability, and responsiveness. This value is associated with loose and informal control, open, and lateral channels of communication, and free flow of information throughout an organisation.
This study employed the definition given by Henri (2006, p.80) where culture is defined as “the shared values that interact with the organisation’s structure and management control system and leads to behavioural changes”. Consequently, this study defines culture from an environmental management perspective, where the organisation’s environmental culture means people in the organisation will share the environmental information which creates and builds the same value within the organisation. Thus, the value is able to change the behavioural aspects of the people in the organisation in order to implement environmental management practices.
2.2Environmental Management Practice
Environmental management practice, usually, represents the environmental management strategy of an organisation. According to Klassen and Whybark (1999), by using environmental management practices, an organisation can determine its environmental strategy. It is also argued by Azzone and Noci (1998) that organisational strategy can be determined by internal and external factors related to environmental issues which are translated by its practice.
In the environmental management literature, there is an argument that it is not possible to standardise practices of environmental management because the term “environmental management” has different meanings to different people. Carmona-Moreno et al. (2004) stated that environmental management involves a variety of environmental practices which differ depending on the industry, the nature of business, and its impact on the environment. In addition, Carmona-Moreno et al. (2004) mentioned that the characteristics of the industry with regard to environmental issues will affect the nature of environmental management practice in organisations. In their study, the characteristics of the hotel sector that involve environmental issues, such as engaging in environmental activities, limited environmental legislation, and active customers, contribute to how the hotel sector responds to their environmental problems. For example, having limited environmental legislation, hotels react to environmental problems by practising environmental management voluntarily and more emphasis on pollution prevention activities.
Berry and Rondinelli (1998) however, suggested that in order to improve performance, each organisation should practice appropriate environmental activities and strategies (for example, environmental proactive strategy). Furthermore, Winn and Angell (2000) agreed that proper implementation of the different environmental practices should result in improvement of the organisation’s environmental performance. Schaltegger et al. (2003) argued that good environmental management practice should have six key functions, which are goal setting, information management, decision support, control, communication and auditing, and review. In order to support all these functions, the environmental management tools that should be considered for implementation include total quality environmental management, life cycle assessment, environmental accounting, environmental reporting, and environmental auditing.
Furthermore, several researchers such as Griffin (1995), Heffelman (1995), Florida (1996), and Garrod and Chadwick (1996), identified significant adoption of environmental management elements among the organisations they studied. These studies revealed broad trends of adoption of environmental practices across industrial sectors and organisational sizes. However, according to Theyel (2000), none of these studies focused on the entire industrial sector as all included fewer than 10 organisations coming from any number of industrial sectors. Therefore, these researchers were prevented from drawing statistically significant conclusions and forming generalised conclusions about the adoption of environmental management in a particular industry.
Basically, organisations practising environmental management will follow environmental management system (EMS) principles, namely plan, organise, command, coordinate, and control. Therefore, this study argues that any practises related to the environment should follow environmental management system principles such as creating an environmental policy, setting objectives, implementing a programme to achieve those objectives, monitoring and measuring its effectiveness, correcting problems, and reviewing the system to improve it, and thereby improving environmental performance.
2.3Environmental Performance
In general, environmental performance is based on the ISO 14031 where this standard provides the guidelines to evaluate environmental performance of organisations. According to Schaltegger et al. (2003), ISO 14031 has been approved throughout the world. As cited in Schaltegger et al. (2003), ISO 14031 proposed three types of indicators to evaluate performance; the environmental performance indicator (EPI), the environmental management indicator (EMI), and the environmental condition indicator (ECI). However, only EPI and EMI are recognised by ISO 14031 as indicators of an organisation’s environmental performance.
Environmental performance is the interaction between business and the environment. The benefit and damage to the natural surroundings brought about by organisations’ activities is mentioned in relation to environmental performance. The other study that contributed towards systematising the dimensions to be included in environmental performance is that by Ilinitch et al. (1998). They integrated the elements of the model of Wood (1991) and Lober (1996) to measure environmental performance and developed the matrix of criteria to evaluate an organisation’s environmental performance using 2 x 2 dimensions; process, output, internal, and external (refer to Figure 1).
                                                   Internal                     External
                     Process                Organisational systems        Stakeholder relations
                     Output                 Regulatory compliance        Environmental impacts
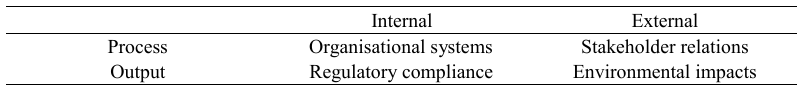
Ilinitch et al.’s (1998) model showed that internal organisational system measures refer to the activities or processes designed to improve organisation’s performance. An external stakeholder relation refers to the interaction between the organisational and external agents, while external environmental impacts include the negative spill over the organisation’s activities have on the environment. Finally, the internal regulatory compliance refers to the degree to which the organisation observes the minimum requisites established by certain norms or laws.
In the hotel sector, Burgos-Jimenez and Lorente (2001) stated that the objective of environmental performance should be understood as reducing the negative effect on the natural environment initiated by the activities of hotels. Similarly, Carmona-Moreno et al. (2004) defined environmental performance as the activities and processes that were designed to minimise the negative impact on the natural environment caused by the productive activities of a company and how people in hotels perceive that associated impact. They focussed on internal processes in evaluating hotel’s environmental performance. The current study refers to environmental performance based on Ilinitch et al.’s (1998) definition and adapted the instruments used by Carmona-Moreno et al. (2004).
2.4EMP, Organisational Culture and EP
Contingency theory argues that design and use of organisational culture is contingent upon the specific circumstances of the setting in which the control system is operating. This idea was discussed by Emmanuel et al. (1990) where the contingency theory is based on the premise that there is no one standard or universal cultural system as a control system that can be applied to all firms in all situations. In terms of environmental management literature, people in organisations should share environmental information that creates value within organisations and be able to change belief systems in order to improve environmental performance.
Hunt and Auster (1990) argued that organisations should implement environmental culture to increase peoples’ willingness to initiate environmental improvements. They argued that organisational culture has a positive effect on environmental performance. According to Hunt and Auster (1990), culture privilege (such as a reward system for employees who perform well in solving environmental problems or incentive systems for those who participate actively in environmental management practice) can be designed to increase employees’ willingness to initiate environmental improvement. Previously, organisational culture was seen as a distinct factor which influences budget (Dunk & Lyson, 1997; O’Connor, 1995) or it was said as a related factor to accounting and reporting practices (Chow et al., 2002).
Simons (1995) argued that organisational culture can boost or hinder organisational performance. Simons (1995) postulated that organisational culture plays an important core value in implementing business strategy and it is deemed to be a primary determinant of the direction of employees’ behaviour (Hasan & Azhar, 2008). Ehtesham, Muhammad, and Muhammad (2011) stated that without considering the impact of organisational culture, organisational practices (such as EMP) could be counterproductive because the two are interdependent and change in one will affect the other.
Therefore, according to contingency theory, organisational culture must change in order to adopt a new perspective implementation within an organisation. Accordingly, it was hypothesised that:
The more extensive the implementation of organisational culture (CULTURE), the greater the effect is of environmental management practice (EMP) on environmental performance (EP) in the hotel sector.
3.0Research Method
3.1Sample and Data Collection
Initially, details of all the 453 hotels in Malaysia were obtained mainly from the Accommodation guide: Malaysia Truly Asia 2004 (the latest version up to 2007). This database was considered to be a sample of the study (based on Finance Ministry’s report, up to 2004, there are in total 2,100 population of hotels in Malaysia). However, after considering the suggestion from previous literature that environmental management practice are most likely to be found in the larger firms, therefore, it was decided to focus on hotels which have more than 50 rooms. After improving the questions so as to eliminate ambiguous questions, questionnaires were mailed to 300 hotels (after deducting small hotels and those involved in the pilot study) with a cover letter assuring anonymity and confidentiality, as well as a stamped self- addressed reply envelope. The questionnaires were addressed to the hygiene manager (where the hotel had an environmental or hygiene department) or general manager (where the hotel did not have an environmental department).
As cited previously, according to Bohdanowitcz (2003), hotel size is grouped based on a formula, where those below 50 rooms are considered to be a small sized hotel, rooms between 50 and 150 is medium sized, and over 150 rooms is considered a large sized hotel. The initial version of the questionnaire was submitted in a pilot test involving 30 hotels that fulfilled the respondent criteria.
Referring to Table 1, the returned questionnaire was 125 cases and the response rate of the current study was 41.7%. Based on comments by Rahman (2001), this response rate was considered reasonably adequate. In order to achieve a high response rate, four steps were adopted (Theyel, 2000; Baba, 2004), namely (i) pre-notification; (ii) initial mailing; (iii) first follow-up, and (iv) second follow-up. The first step involved a letter, phone call, or e-mail to respondents to promote initial interest of the issues raised. Then, mail was sent to the environmental or hygiene managers in the sample, including the cover letter, questionnaire, and business reply envelope. In some circumstances, such as hotels which did not have a full address on the database, the questionnaire was sent by fax or e-mail. The first follow-up was a postcard reminder, while the second was a phone call or replacement questionnaire sent to those who had not answered.
| Total hotels listed in the accommodation guide (exclude budget accommodation) | 453 | |
| (-) Pilot sample | (30) | |
| Total hotels considered as the sample of the study | 423 | |
| (-) Hotels less than 50 rooms | (123) | |
| Total hotels used as a sample of the study | 300 | |
| Mailed questionnaire (m) | 300 | 100% |
| Returned questionnaire (n) | 125 | 41.7% |
3.2Variables and Measurement
3.2.1Organisational Culture
In this study, organisational culture is measured using an adapted version of Henri’s (2006), and Eker and Eker’s (2009) instruments which were based on a competing-values perspective developed by The National Centre for Higher Education Management System. This instrument was validated and has been used recently in an accounting setting (Bhimani, 2003). However, to better reflect the environmental context related to the unit of analysis, the statements used are slightly modified.
This instruments asks respondents to distribute 100 points among four cultural types, which best describes their hotel, within each of the four dimensions of culture; institutional character, institutional leader, institutional cohesion, and institutional emphasis (refer to appendix A). For each dimension, respondents must distribute 100 points among four sentences where sentence A refers to group culture, sentence B refers to development culture, sentence C refers to hierarchical culture, and sentence D refers to rational culture.
Following the approach of Henri (2006), the present study attempted to capture the specific position of each organisation on the control value and the flexibility value (dominant type). The summation of the group-culture score and the development-culture score gives the flexibility-value score, while the summation value of the hierarchical-culture score and the rational-culture score gives the control-value score2. Then, the dominant type of culture of the organisation can be accessed through the different scores of flexibility value and control value.
According Agbejule (2011), flexibility-value score is equal to group-culture score plus development- culture score while control-value score is equal to hierarchical-culture score plus rational-culture score. A positive value means a flexibility-dominant type of culture and negative value means a control-dominant type of culture. In order to standardised the score, the answer scale was re-coded to a five-point scale where the answer between range 0 to 20 is recoded as 1, 20 to 40 is recoded as 2, 40 to 60 is recoded as 3, 60 to 80 is recoded as 4, and 80 to 100 is recoded as 5.
The items load into two factors that were factor 1 as a flexibility value and factor 2 as a control value. Factor 1 (flexibility value) has eigenvalue 1.338 with 66.897% variance explaining the common factor (Cronbach-alpha is 0.603). On the other hand, factor 2 (control value) has eigenvalue 1.267 with 63.372% variance and 0.522 Cronbach-alpha. The dominant value of culture can be accessed by subtracting flexibility value from control value. A positive score captures flexibility value dominant type, while a negative score refers to a control dominant type. The type of dominant value adopted by hotels shows the hotels’ involvement in environmental management practice.
3.2.2EMP
The measure of EMP was drawn from an instrument used by Carmona-Moreno et al. (2004) and Gil et al. (2001). The adapted instrument consists of 22 items measured through a five-point scale, ranging from 1 (very little commitment) to 5 (very strong commitment) (refer to Appendix B).
___________ For example: Case 1
GROUP DEV HIERARCHICAL RATIONAL FLEX CONTROL DOMINANT
Therefore, dominant type of culture for this case is flexibility control system, where dominant can be gained from flexibility value (group + development) minus control value (hierarchical + rational). Hotels were asked to state whether or not they were carrying out a number of EMP to prevent negative environmental impacts. A mean score was computed where a high mean score indicates a high level of commitment which represents a proactive environmental strategy. Splitting at the median of EMP, two sub-samples were created, where scores higher (lower) than the median were labelled high (low) commitment. This type of splitting was also used by Bisbe and Otley (2004).
Factor analysis indicated that the 20 remaining items loaded into a single factor (percentage of common variance explained is 75.052%), which supported the one dimension of the measurement instrument. The internal consistency of the items included in the scale was assessed using Cronbach-alpha as a reliability coefficient and resulting alpha was 0.982, which is above the 0.70 acceptance value as recommended by Nunnally (1978).
3.2.3 EP
This study defined EP based on subjective measurement and does not intend to look at objective figures, such as how much waste is reduced. The current study adapted the EP measurement by Carmona-Moreno et al. (2004), since their measurement was purposely developed and validated to measure hotels’ EP (refer to Appendix C). They developed a measurement scale that adequately covers physical and societal aspects of EP of the hotel sector and does not require any quantitative information.
Respondents were asked to provide answers on a five-point scale ranging from 1=strongly disagree to 5=strongly agree for environmental improvement statements. A mean score was calculated whereby the highest mean score indicates better EP.
Factor analysis indicated that all items of EP loaded onto a single factor (percentage of common variance explained was 77.67%) that supported the unidimensionality of the measurement instrument. The Cronbach-alpha of the EP items was 0.959 which explained that the reliability coefficient of internal consistency is higher than the expected level (0.70).
3.3Data Analysis
In order to test the moderating effect of organisational culture on the relationship between EMP and EP, moderated hierarchical multiple regressions was used. This method was first suggested by Baron and Kenny (1986).
4.0Results
The present study shows how the interaction of EMP and organisational culture influences EP. The inter- correlation in Table 2 indicates that organisational culture is significantly and positively correlated to both EMP and EP.
| CULTURE | EMP | EP | |
|---|---|---|---|
| CULTURE (control/flexibility) 1 | |||
| EMP | 0.234** 1 | ||
| EP | 0.178** | 0.261** 1 | |
4.1Hypothesis Test
The hypothesis of the study required a test on the interaction effect of organisational culture and EMP on EP. The moderating effect happens when the level of the third variable (in this case the organisational culture) influences or affects the degree of relationship between two variables (in this case the EMP and EP).
Baron and Kenny (1986) suggested that in order to test the moderating effect, moderated hierarchical multiple regression analysis should be used. This suggestion was supported by Bisbe and Otley (2004), and Harrington and Kendall (2006) who argued that the moderated multiple regression analysis allows the relationship between the independent variables and dependent variables count on the other independent variables (i.e., moderator).
This proposal can be tested using the formulation of the moderation model as shown below:
EP = α + β1EMP + β2CULTUREi + β3EMP*CULTUREi + ε
Where
EP is environmental performance, CULTURE is organisational culture, EMP is environmental management practice, and EMP*CULTUREi is interaction term.
Model 1 in Table 3 gives the regression results for EMP and EP. The result indicated that EMP has a positive significant effect on EP. The standardised coefficient is 0.025 and significant at p<0.001. Model 2 in Table 3 shows the result for the same regression with the addition of the CULTURE which is not significant at p>0.01. Table 3 highlights that when using organisational culture as a moderator (Model 3), the interaction coefficient is significant but negative sign. The R2 = 0.123 and the interaction term adds 4.0% to the explanation power to explain the variation in environmental performance.
| Variable | Model 1 | Model 2 | Model 3 |
|---|---|---|---|
| EMP | 0.261*** (0.025) | 0.232* (0.025) | 0.205 *(0.025) |
| CULTURE | 0.124 (0.006) | 0.603 *(0.212) | |
| EMP*CULTURE | -0.514*(0.003) | ||
| R2 | 0.068*** | 0.067** | 0.123 |
| R2 Change | 0.015 | 0.040 | |
| F Change | 8.301*** | 1.919 | 5.486* |
| *p<0.05 **p<0.01 ***p<0.001 All betas are standardised. |
Figure in bracket indicates the standard errors. Bold figure highlights the significance of the relationship. Even though, the study postulated that there will be a positive and direct relationship between organisational culture and EP in the hotel sector, this expectation was not supported as indicated in Table 3, Model 2 above.
In order to provide further evidence, Table 4 shows that just over half of the sampled hotels in Malaysia employed control dominant value in their organisational culture. Based on previous literature, for example Henri (2006), control-type of culture is more stringent and thus it is possibly more difficult to change and adopt a new system. Table 4 reveals the insignificant relationship between the types of culture and environmental performance.
| Environmental | Hotel’s environmental culture (CULTURE) | Total | |
|---|---|---|---|
| performance (EP) | Flexibility dominant | ||
| Control dominant | |||
| value(0) | value (1) | ||
| Less than median (0) | 38 (59.4%) | 26(43.3%) | 64 |
| Better than median | 26(40.6%) | 34(56.7%) | 60 |
| (1) | |||
| Total | 64 Value = 2.581 | 60 Sig. = 0.108 (p>0.05) | 124 |
Therefore, the statement which postulated that there is a positive and direct relationship between organisational culture and environmental performance is rejected. The results suggested that there is no significant direct relationship between environmental performance and hotels’ culture. Hotels that employ flexibility-type of culture will possibly portray better environmental performance.
Overall, theoretical development suggests that the nature of the relationship between environmental management practice and environmental performance is diversified and varied. The variety depends on the extent organisations implement or extensively use management control systems in the environmental management context.
By using ANOVA, the interaction effect can be drawn between the environmental management practice and the environmental performance. CULTURE was split at median level into two groups, namely control-type and flexibility-type of culture. As shown in Figure 2, when hotels which have low commitment in practising environmental management activities, but engage in flexibility-value in environmental culture, they will have higher environmental performance, otherwise, engaging in control- dominant type value, they will have lower environmental performance.
5.0Discussion and Conclusion
The result of the study sheds some light on the relationship between EMP and organisational culture. Organisational culture was found to be not significantly related to the level of environmental performance (Model 2 in Table 3). This result suggests that culture does not act as a factor to ensure hotels will achieve better environmental performance. Hunt and Auster (1990) suggested that firms should implement organisational culture related to environmental issues to increase people’s willingness to initiate environmental improvement. However, in this present study, even though hotels create an environmental culture in their activities, if people are not ready to share their knowledge toward the creation and change of values and beliefs, better environmental performance may not be achieved. Most of the sampled hotels in Malaysia employ a control dominant type of culture which refers to formality, rigidity, and more strictness and tightness in achieving objectives. All the activities carried out are rigid and not flexible. Thus, adaptability to a new strategy is more difficult. This finding is similar to the traditional control system where formal and control feedback is considered vital to achieve better performance (Anthony, 1965). However, as Simons (1987) suggested, the new emerging issues such as environmental issues should be opened to new ideas in order for the organisation to change and respond to enhanced environmental performance.
On the other hand, this insignificant finding may be due to the environmental issues being a new concern in the Malaysian environment and not currently properly managed by the hotel sector (Kasim & Scarlat, 2007). One reason may be related to interactive action from the top management and employees. If people in the hotels are not well trained, the knowledge and skills may not be developed and shared properly. Thus, new values and beliefs cannot be created and consequently, the attitude of people toward environmental issues would not change. Furthermore, the result also showed that interaction between environmental management practices and environmental culture (EMP*CULTURE) has a negative significant effect on environmental performance. This interaction also influenced the effect of environmental management practice on environmental performance by increasing the explanatory power of the model. The coefficient is opposite from expected. A negative coefficient of interaction effect of environmental management practice and environmental culture suggests that the more hotels integrate and use environmental culture in environmental management practice, the less the effect on environmental performance, while the less the hotels consider the environmental culture in their environmental management practices, the greater the effect on environmental performance. Without an interaction effect, environmental culture has no significant effect on environmental performance. Environmental performance, statistically, is similar between hotels that are committed to environmental management practice by employing flexible type of culture and those who are not committed to environmental management practice by employing control- type of culture. By entering the interaction between environmental culture and environmental management practice, hotels who commit differently appear to have different levels of environmental performance.
This study provided evidence on the importance of having correct organisational culture in the organisation. In conclusion, the results suggested that in order to achieve better environmental performance, the management and employees should be ready and flexible to accept new ideas and share a belief system which leaves them open toward new ideas (environmental matters). Even though hotels can create and use a new culture extensively, without willingness to adapt to a new environment, the hotels may not meet their objectives in reducing environmental impact. This study has important implications for management practices.
References
- Agbejule, A. (2011). Organisational culture and performance: the role of management accounting system. Journal of Applied Accounting research, 12(1), 74-89.
- Anthony, R. N. (1965). Planning and control systems: A framework for analysis. Cambridge: Harvard University Press.
- Armstrong, J. S., & Overton, T. S. (1977). Estimating non-response bias in mail surveys. Journal of Marketing Research, 14, 396-402.
- Azzone, G., & Noci, G. (1998). Identifying Effectives PMSs for the Deployment of Green Manufacturing Strategies. International Journal of Operations and Production Management, 18(4), 308-335.
- Baba, H. N. (2004). Corporate social responsiveness and environmental performance of Small Medium Enterprise: An empirical study. Unpublished Thesis, University Utara Malaysia.
- Baron, R. M., & Kenny, D. A. (1986). The moderator-mediator variable distinction in social psychological research: Conceptual, strategic and statistical consideration. Journal of Personality and Social Psychology, 51(6), 1173-1182.
- Berry, M. A., & Rondinelli., D. A. (1998). Proactive corporate environmental management: A new industrial revolution. Academy of Management Executives, 12(2), 38-50.
- Bhimani, A. (2003). A study of the emergence of management accounting system ethos and its influence on perceived system success. Accounting, Organisation and Society, 28(6), 523-638.
- Bisbe, J., & Otley, D. (2004). The effects of the interactive use of management control systems on product innovation. Accounting, Organisation and Society, 29(8), 709-737.
- Bohdanowicz, P. (2003). Environmental awareness in the Hotel industry (Final Report). Sweden: Royal Institute of Technology Stockholm.
- Burgos-Jimenez, J. D., & Lorente, J. J. C. (2001). Environmental performance as an operation objective. International Journal of Operations and Production Management, 21(12), 1553-1572.
- Carmona-Moreno, E., Cespedes-Lorente, J., & Burgos-Jimenez, J. D. (2004). Environmental strategies in Spanish hotels: Contextual factors and performance. The Service Industries Journal, 24(3), 101-130.
- Chow, C. W., Harrison, G. L., MacKinnon, J. L., & Wu, A. (2002). The firm culture of public accounting firms: Evidence from Taiwanese local and US affiliated firms. Accounting, Organisation and Society, 27(4-5), 347-385.
- Deshpande, R. & Webster, F. E., Jr. (1989). Organisational culture and marketing. Defining the research agenda. Journal of Marketing, 53(January), 3-15.
- Dunk, A. S., & Lysons, A. F. (1997). An Analysis of Departmental Effectiveness, Participative Budgetary Control Process and Environmental Dimensionality within the Competing Values Framework: A Public Sector Study. Financial Accountability Management, 13(1), 1-15.
- Ehtesham, U. M., Muhammad, T. H., & Muhammad, S. A. (2011). Relationship between organisational culture and performance management practices: A case of University in Pakistan. Journal of Competitiveness, 4, 78-86.
- Eker, M., & Eker, S. (2009). An Empirical analysis of the association between the organisational culture and performance measurement systems in the Turkish Manufacturing Sector. Journal of Economic and Social research, 11(2), 43-76.
- Emmanuel, C., Otley, D., & Merchant, K. A. (1990). Accounting for Management Control (2nd ed.). London: Chapman and Hall.
- Florida, R. (1996). Lean and green: The move to environmentally conscious manufacturing. California Management Review, 39(1), 80-105.
- Foo, S. I., & Tan, M. S. (1988). A comparative study of social responsibility reporting in Malaysia and Singapore. Pacific Sociological Review, 18, 12-15.
- Garrod, B., & Chadwick, P. (1996). Environmental management and business strategy towards a new strategic paradigm. Futures, 2, 5-6.
- Gil, M. J. A., Jimenez, J. B., & Lorente, J. J. C. (2001). An analysis of environmental management, firm context and performance of Spanish Hotels. OMEGA The International Journal of Management Science, 29(6), 457-471.
- Gu, V. C., Hoffman, J. J., Cao, Q., & Schiniederjans, M. J. (2013). The effects of organisational culture and environmental pressures on IT project performance. International Journal of Project Management. http://dx.doi.org/10.1016.
- Griffin, G. (1995). The results of the PPR’s 1994-95 survey: Industry’s P2 practices. Pollution Prevention Review. Spring.
- Harrington, R. J., & Kendall, K. W. (2006). Strategy implementation success: The moderating effects of size and environmental complexity and the mediating effects of involvement. Journal of Hospitality and Tourism Research, 30(2), 207-230.
- Hasan, F., & Azhar (2008). Relationship between contextual variables andmanagement control systems: Experience with Indonesian hospitality industry. Proceeding of the International Conference of American Accounting Association AAA-event-2008.
- Heffelman, L. (1995). Environmentally sound manufacturers. Pollution Prevention Review. Spring.
- Henri, J. F. (2006). Firm culture and performance measurement systems. Accounting, Organisation and Society, 31(1), 77-103.
- Henri, J. F., & Journeault, M. (2006). Eco-control: The influence of management control systems on the environmental and economic performance. Paper presented at the Management Accounting Conference 2006.
- Hunt, C. B., & Auster, E. R. (1990). Proactive environmental management: Avoiding the toxic trap. Sloan Management Review, Winter, 7-18.
- Ilinitch, A. Y., Soderstorm, N. S., & Thomas, T. E. (1998). Measuring corporate environmental performance. Journal of Accounting and Public Policy, 17, 383-408.
- Jaafar, R. (2001). Pelaporan maklumat alam sekitar di Malaysia: Kajian kebolehpercayaan dan faktor yang mempengaruhi. Unpublished PhD Thesis, University Kebangsaan Malaysia.
- James, P. (1994). Business environmental performance measurement. Business Strategy and the Environment, 3(2), 59-67.
- Kasim, A., & Scarlat, C. (2007). Business environmental responsibility in the Hospitality industry. Management, 2(1), 5-23.
- Klassen, R. D., & Whybark, D. C. (1999). Environmental Management in Operation: The Selection of Environmental Technologies. Decisions Sciences, 30(3), 601-631.
- Lober, D. J. (1996). Evaluating the environmental performance of corporations. Journal of Managerial Issues, 8(2), 184-205.
- Maria, P. B. (2011). The relationship between performance and organisational culture. Journal of Defence Resource Management, 2(2), 137-142.
- Miller, J., & Szekely, F. (1995). What is “green”? European Management Journal, 13(3), 322-333.
- Nunnaly, J. C. (1978). Psychometric Theory. New York: McGraw Hill Company.
- O’Connor, N. G. (1995). The influence of organisational culture on the usefulness of budget participation by Singaporean-Chinese managers. Accounting, Organisation and Society, 20(5).
- Ognonna, E. & Harris, L. (2000). Leadership style, organisational culture and performance: Empirical evidence from UK companies. International Journal of Human Resource Management, 11(4), 766-788.
- Rahman, A. S. (2001). Total quality management practices and business outcome: evidence from small and medium enterprises in Western Australia. Total Quality Management, 12(2), 201-210.
- Romlah, J., Takiah, M. I., & Nordin, M. (2002). An Investigation of Environmental Disclosure in Malaysia. Paper presented at the AANZ, New Zealand.
- Rousseau, D. M. (1990). Organisational culture: The case for multiple methods. In B. Schneider (Ed.), Organisational culture and Leadership. San Francisco: Jossey-Bass.
- Sadri, G., Lees, B. (2001) Developing corporate culture as a competitive advantage. Journal of Management Development, 20(10). Pp. 853-859.
- Schaltegger, S., Burritt, R., & Petersen, H. (2003). An introduction to corporate environmental management: Striving for sustainability. Sheffield, UK: Greenleaf Publishing Limited.
- Schein, E. (1990). Organisational culture. American Psychologist, 45(2), 109-119.
- Schylander, E. (2004). Environmental effect and firm experience of environmental management system. Lulea University of Technology.
- Sharma, S. (2000). Managerial interpretations and organisational context as predictors of corporate choice and environmental strategy. Academy of Management Journal, 43(4), 681-697.
- Shrivastava, P. (1995). Environmental technologies and competitive advantage. Strategic Management Journal, 16(3), 183-200.
- Simons, R. (1987). Accounting control system and business strategy: An empirical Analysis. Accounting, Organisation and Society, 12(4), 357-374.
- Simons, R. (1990). The role of management control system in creating competitive advantage: New perspective. Accounting, Organisation and Society, 12(4), 357-374.
- Simons, R. (1995). Levers of control: How managers use innovative control systems to drive strategic renewal. Boston: Harvard University Press.
- Sorensen, J. B. (2002). The strength of corporate culture and reliability of firm performance. Administrative Science Quarterly, 47 (March), 70-91.
- Theyel, G. (2000). Management practices for environmental innovation and performance. International Journal of Operations and Production Management, 20(2), 249-266.
- Wackernagel, M., & Rees, W. (1996). Our ecological footprint: Reducing human impact on the Earth. Canada: New Society Publisher.
- Wagner, M., & Schaltegger, S. (2004). The effect of corporate environmental strategy choice and environmental performance on competitiveness and economic performance: An empirical study of EU manufacturing. European Management Journal, 22(5), 557-572.
- Winn, M. I., & Angell, L. C. (2000). Towards a process model of corporate greening. Organisation Studies, 21(6), 1119-1147.
- Wood, D. J. (1991). Towards improving corporate social performance. Business Horizons, 34(4), 66-74.